
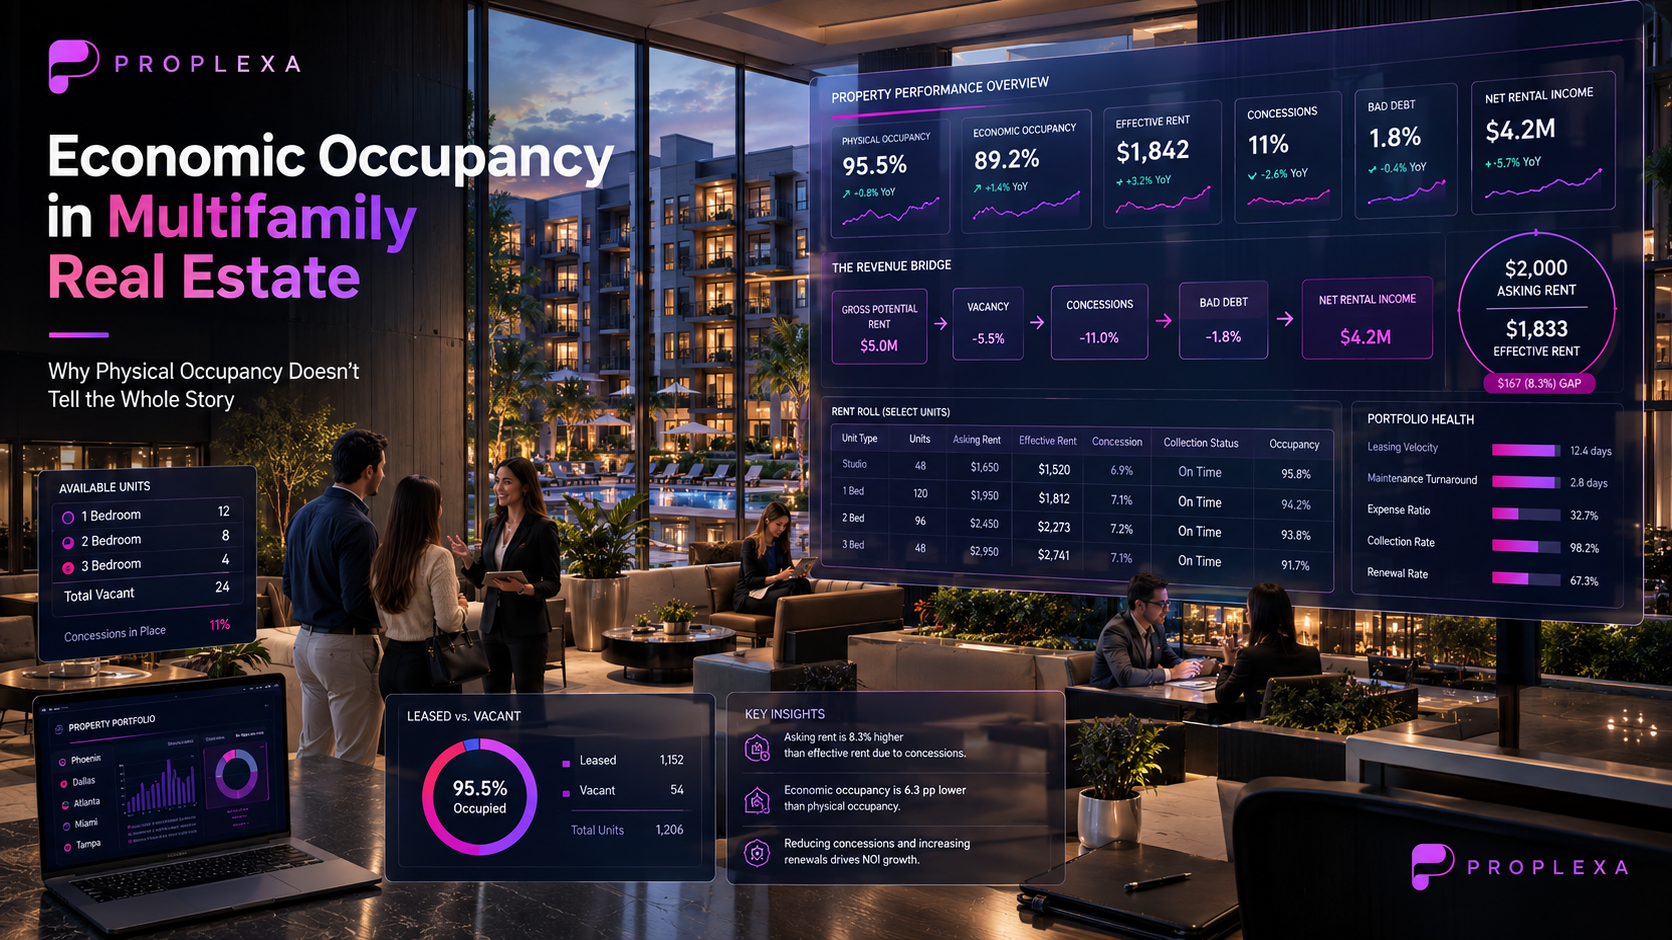
For years, investors have often looked at physical occupancy as one of the fastest ways to judge apartment performance.
If a property is 95% occupied, it appears healthy.
But occupancy alone does not tell you how much rental revenue the property is actually collecting.
A property can be physically occupied while simultaneously giving away rent through concessions, carrying delinquent balances, or leasing units below their potential rental value.
That is why sophisticated owners should distinguish between physical occupancy and economic occupancy.
In 2026, that distinction matters more than ever.
Physical Occupancy Is Not the Same as Economic Performance
Physical occupancy answers a relatively simple question:
What percentage of units are occupied?
Economic occupancy asks a more important financial question:
What percentage of the property's potential rental income is actually being realized?
This distinction becomes critical when a property is using concessions, experiencing collection problems or offering aggressive discounts to maintain occupancy.
Fannie Mae's 2026 multifamily underwriting framework explicitly separates physical vacancy, concessions and bad debt when calculating Net Rental Income (NRI).
In simplified terms:
Gross Potential Rent − Vacancy − Concessions − Bad Debt = Net Rental Income
That is much closer to the revenue that ultimately supports NOI.
The 2026 Concession Problem
The national multifamily market illustrates why this matters.
According to RealPage, in August 2026, 15.4% of stabilized U.S. apartment units were offering concessions. The average concession was 11% of asking rent, approximately equivalent to 5.7 weeks of free rent on a 12-month lease.
That means an apartment can be technically occupied while producing materially less revenue than its nominal asking rent suggests.
And the pressure is not distributed evenly.
RealPage reported that Class C properties had the highest concession usage in July, while efficiency units also experienced particularly high concession levels.
For owners, the implication is straightforward:
A full building does not necessarily mean a full revenue stream.
Consider a Simple Example
Imagine a 200-unit property with:
- Average asking rent: $1,800
- Gross Potential Rent: $4.32 million
- Physical occupancy: 95%
At first glance, the property appears strong.
But suppose the property also experiences:
- 5% physical vacancy
- $150,000 in concessions
- $75,000 in bad debt
The property is not economically performing at 95% of potential revenue.
Its actual rental income is reduced by multiple forms of revenue leakage.
This is why comparing properties using only physical occupancy can produce misleading conclusions.
Economic Occupancy Should Be Decomposed
Rather than tracking one headline number, owners should monitor the components separately.
1. Physical Vacancy
Units that are genuinely unoccupied.
This is usually the most visible form of revenue loss.
2. Concessions
Free rent, move-in incentives, discounts and other incentives granted to residents.
Concessions can temporarily support leasing velocity while simultaneously reducing effective revenue.
3. Bad Debt
Rental income that was billed but ultimately becomes uncollectible.
This is particularly important because it represents a different operational problem from physical vacancy.
A vacant apartment needs a lease.
A delinquent apartment needs effective collections and resident-account management.
4. Loss-to-Lease
The difference between market rent and the rent actually being collected under existing leases.
A property may have excellent occupancy while still carrying significant embedded rental-rate leakage.
Why Effective Rent Matters
Investors should increasingly compare effective rent, not simply asking rent.
For example:
An apartment advertised at $2,000/month with one month free on a 12-month lease produces an effective monthly rent of approximately:
$1,833
The advertised rent may look strong.
The economics tell a different story.
This distinction becomes especially important when comparing competing properties, evaluating property-manager performance or underwriting acquisitions.
2026 Makes This Metric More Important
RealPage reported that U.S. apartment occupancy reached 95.5% in Q2 2026, while annual demand remained below the decade average and concessions continued to be widespread.
Meanwhile, Yardi Matrix reported that national multifamily rent growth remained modest, with its August 2026 forecast calling for approximately 1.4% rent growth for the full year.
In other words, owners cannot assume that simply increasing asking rents will solve revenue-growth challenges.
The quality of revenue realization matters.
What Owners Should Ask Their Property Manager
A sophisticated owner should request more than a monthly occupancy percentage.
Ask for:
- Physical occupancy
- Economic occupancy
- Gross Potential Rent
- Actual collected rent
- Concessions as a percentage of GPR
- Bad debt as a percentage of GPR
- Loss-to-lease
- Average effective rent
- Renewal effective rent
- New-lease effective rent
- Collection rate
- Delinquency aging
- Month-over-month revenue variance
The goal is to understand where the gap between potential revenue and realized revenue originates.
Economic Occupancy Is Also an Asset-Management Metric
This is not merely an accounting exercise.
Revenue leakage directly affects NOI.
If a property generates $6 million in potential rental revenue but realizes $5.6 million after vacancy, concessions and bad debt, the $400,000 gap deserves the same analytical attention as a $400,000 increase in operating expenses.
The operational response, however, depends on the source.
If the problem is vacancy, the solution may involve pricing, marketing, leasing velocity or unit readiness.
If it is concessions, the issue may be competitive positioning or lease-up strategy.
If it is bad debt, collections and resident screening become more important.
If it is loss-to-lease, renewal and pricing strategy may be the underlying issue.
The number tells you there is leakage. The decomposition tells you what to fix.
How Property Managers Should Be Evaluated
This creates a better framework for evaluating property management companies.
Instead of asking:
“What is the property's occupancy?”
Owners should ask:
“How efficiently is the property converting potential rent into collected revenue?”
That shift moves property management from a service discussion toward measurable asset performance.
A strong management relationship should make revenue leakage visible, explain its causes and establish measurable actions to reduce it.
Where Proplexa Fits
Proplexa is built around a simple principle:
Property owners should be able to compare property management companies based on meaningful performance—not just reputation or a management fee.
An RFP can be structured around the operational realities that actually affect property economics:
- Leasing strategy
- Collections
- Resident retention
- Revenue management
- Maintenance
- Vendor management
- Reporting
- Technology
- Financial controls
When management proposals are evaluated side by side, owners can move beyond:
“Who manages properties like mine?”
and toward:
“Who has the operating model to protect the economics of my property?”
The Bottom Line
Physical occupancy remains important.
But it is only one part of the revenue equation.
In 2026, with concessions still elevated and rent growth relatively modest, investors should pay closer attention to economic occupancy, effective rent, vacancy loss, concessions and bad debt.
The property that looks 95% occupied may not be the property producing the strongest economic result.
Measure the rent you can theoretically earn. Then measure the rent you actually collect. The gap is where the management opportunity lives.